
Jakarta, ThedailyID — Indonesia needs to modernize its corporate social responsibility (CSR) tax rules to support urgent social and environmental goals, tax expert Arianta John Bangun said.
The Ideatax partner argued that current regulations limit the tax benefits companies can receive for their social and environmental contributions. As a result, spending on stunting prevention, ecosystem restoration, renewable energy, and decarbonization often falls outside eligible tax deductions.

Under Indonesia’s Income Tax Law, businesses can deduct certain expenses related to earning and maintaining income. However, the law generally excludes donations and grants unless specific regulations allow them.
Government Regulation No. 93 of 2010 limits deductible CSR spending to five categories. These include national disaster relief, research and development, educational facilities, professional sports development, and social infrastructure.
John said the existing framework needs a broader review. He also pointed to the 5% cap on the previous year’s net fiscal income and strict administrative requirements as potential barriers to wider corporate participation.
He urged the government to include stunting prevention in the list of eligible expenses.
“The government could consider including donations for stunting prevention and management as deductible expenses from gross income,” John said. He added that the change would give companies greater certainty when supporting a major national health priority.
John also called for tax incentives for businesses investing in environmental restoration, renewable energy, and decarbonization. However, he stressed that the government must establish clear, measurable criteria to prevent misuse.
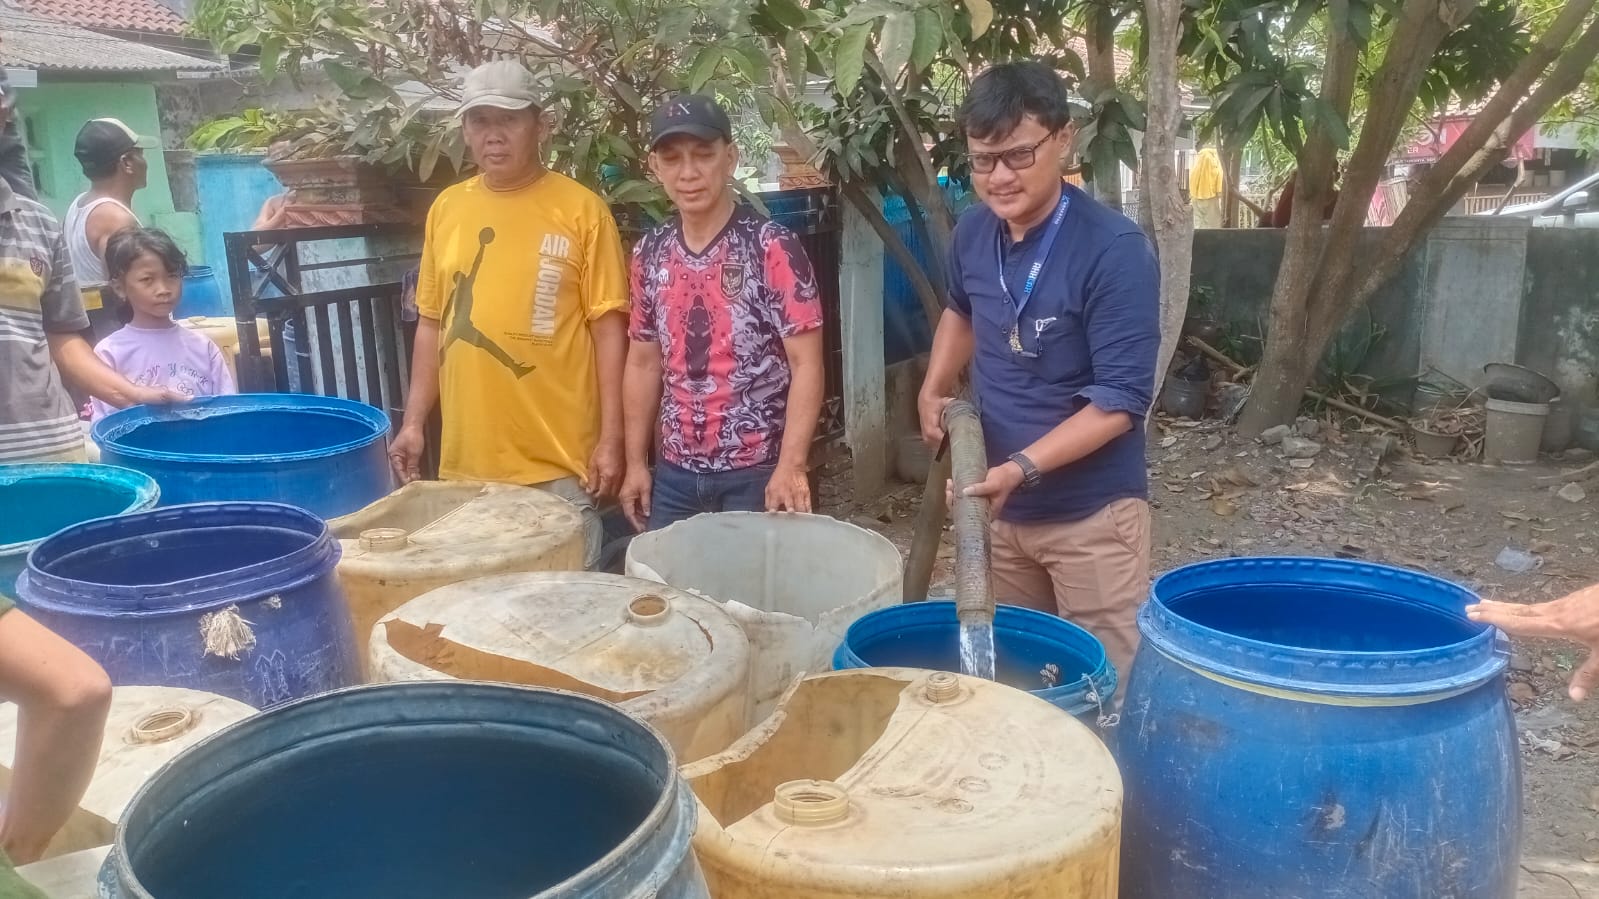
Disaster relief also needs broader coverage, he said. Current rules focus on disasters declared at the national level. John suggested extending deductions to designated regional disasters so companies can help affected communities more quickly while maintaining accountability.
Indonesia already offers some targeted tax incentives. For example, Finance Ministry Regulation No. 128/PMK.010/2019 provides a super tax deduction of up to 200% for certain vocational training and apprenticeship activities.
However, John said broader incentives must come with clear legal rules, simpler administrative procedures, and effective oversight.
“Incentives must be designed with clear rules and adequate oversight mechanisms,” he said. “Legal certainty is essential so that companies can participate confidently without facing ambiguity regarding their tax treatment.”
John said modernizing CSR tax policies could encourage more private-sector funding for sustainable development while maintaining corporate tax compliance.